Key Takeaways
- Limited or no U.S. credit history is one part of a mortgage application; it does not, by itself, describe a borrower’s entire financial situation.
- Income, assets, existing obligations, documentation and the planned property purchase are all useful topics to discuss with a lender.
- Starting the conversation early allows more time to identify documents and address questions before a purchase deadline.
Buying a Home in the U.S. With Limited U.S. Credit History
For families planning a life in the United States, buying a home is an important step. The first question is sometimes more basic than price or interest rate: “Will a lender consider my situation?” That concern can be especially strong for people who recently moved to the U.S., have little U.S. credit history, or earn most of their income overseas.
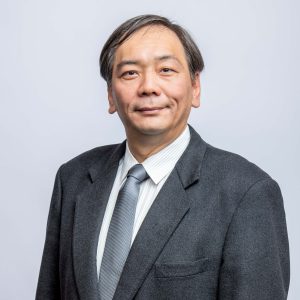
Howard Lee, Senior Vice President, Director of Consumer & Retail Lending, says many prospective buyers come to him with that question before they ask about loan terms. Each application is different, and a conversation about the full financial picture can help buyers understand what information a lender may need to review.
Start With Your Full Financial Picture
A standard mortgage application often draws heavily on U.S. credit and income records. A buyer who recently arrived from abroad may not yet have much of a U.S. credit file, even if they have managed their finances responsibly elsewhere.
Another buyer may have significant assets but receive income primarily outside the United States. These circumstances call for a careful review of what can be documented and how the lender evaluates the application.
When you speak with a lender, be ready to explain where you live, how you earn income, what assets you plan to use for the purchase, and whether another borrower will apply with you. The lender can then explain its documentation requirements and whether any available loan programs may fit your circumstances. Eligibility, terms and approval depend on the complete application and underwriting review.
Plan for Documents and Timing
For one family Howard assisted, a daughter’s acceptance to a school in Northern California prompted the parents to buy a home nearby. The mother and daughter would live in the United States while the father continued to travel between countries. Because the family’s income came largely from overseas, gathering and confirming documents across time zones added work to an already tight schedule before the school year began.
The team completed that particular loan process in a little over 20 days. The timing reflected the facts and preparation in that individual case; it is not a standard processing time. Its practical lesson is to discuss your intended purchase and timeline early, especially when records or signatures may need to move between countries.
Discuss Every Borrower’s Circumstances
Another couple Howard assisted wanted to buy their first home in Irvine. The husband had lived in the U.S. for years, but his income alone did not support the amount they hoped to borrow. Including his wife’s income was important to the application, yet she had only recently arrived and had no U.S. credit history.
The couple initially believed that one incomplete U.S. credit file would prevent them from applying together. After a review of their circumstances, they were able to purchase the home. Their experience illustrates why it is useful to discuss the complete application with a lending team before assuming that a missing U.S. credit history rules out every option. It does not mean that every borrower in a similar situation will qualify.
“Many clients aren’t lacking the ability to buy a home. They’re lacking the confidence to take the first step.”
Questions to Ask a Mortgage Lender
If your finances span countries or you are new to U.S. credit, these questions can help you prepare for an initial conversation:
- What income and asset documentation will you need from each borrower?
- How will you review an applicant with limited or no U.S. credit history?
- Will any overseas documents need translation or additional verification?
- When should we begin the application if our purchase has a firm deadline?
- Which costs, conditions and next steps should we understand before moving forward?
Take the First Step With a Conversation
A home purchase can be part of a larger family plan: supporting a child’s education, settling into a new community, or maintaining a home while life continues across borders. If you are unsure how your credit history or income will be evaluated, sharing your circumstances with a mortgage lender is a practical place to begin.
To discuss home lending options that may fit your situation, contact New Omni Bank’s Consumer Lending team at (626) 913-1818. You can also send us a message or visit one of our branches.
This article is adapted from content originally published in collaboration with Chinese L.A. Daily News.
The information provided in this blog is for general informational purposes only and should not be considered legal, financial, or investment advice. All content is subject to change without notice. Please consult with a qualified professional or contact New Omni Bank directly for personalized guidance or the latest product information.