Key Takeaway
- For cross-border families, a U.S. banking need is often connected to education, homeownership, business activity, or other plans that may come later.
- Before opening an account or arranging a transfer, consider how funds will move, be used, and be managed over time.
- Sharing the fuller picture with your banker can make it easier to discuss banking services that may become relevant as your needs change.
- A bank cannot replace legal, tax, or other professional advisors, but a long-term banking relationship can help clients recognize when it may be useful to seek their advice.
How to Prepare for U.S. Banking When Your Life Spans Two Countries
Opening a U.S. bank account or arranging an initial transfer can feel like a straightforward task. For many families whose lives span more than one country, however, it is often the first step in a longer U.S. journey.
That journey may eventually involve education expenses, a home purchase, a growing business, or more time spent in the United States as a family. Thinking about those possibilities early does not mean you need every decision made today. It simply helps you begin the banking conversation with a clearer picture of what may come next.
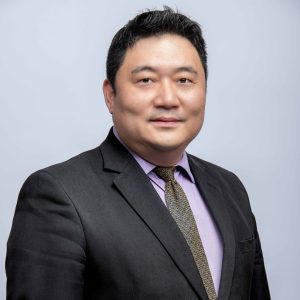
Leon Sung, Managing Director and Chief Business Officer, sees this often among internationally connected clients.
“Many people think they need a U.S. bank account,” Leon says. “What they are really beginning is the process of building a life in the United States.”
Here are four questions that can help you prepare for that conversation.
1. What do you expect to need in the United States over the next few years?
Start with the immediate purpose, but look one or two steps ahead. Will the account be used primarily for living expenses? Are you preparing for a child to study in the United States, considering a home purchase, or exploring a U.S. business opportunity?
Each of these paths can eventually involve different services — financing, a business account, international payments, or cash-management services. You do not need a detailed plan; identifying the directions you are considering can help your banker understand which needs may be relevant now and which may arise later. All loan applications are subject to underwriting and approval.
2. How will funds move to and within the United States?
Consider the expected sources and uses of funds. Will money arrive from overseas periodically? Will you make recurring payments for tuition, rent, a mortgage, or household expenses? Will business-related payments become part of the picture?
Having this context ready can make it easier to discuss the appropriate account setup and banking services for the way you expect to use them.
3. Who will need to use or manage the accounts?
A cross-border household may involve more than one person. A spouse may be managing expenses in another country, a child may be studying in the United States, or a business may have owners or authorized users who need access to banking services.
Discussing who will be involved helps ensure that the bank understands your household or business structure and can explain the available options and requirements.
4. When should you involve other professionals?
Banking is one part of a cross-border life, but it is not the only part. Tax, legal, immigration, estate, and other specialized questions may require guidance from qualified professionals in those fields.
A long-term banking relationship cannot replace those advisors. It can, however, make it easier for the bank to understand how your banking needs connect and recognize when it may be useful to bring other expertise into the conversation.
Why one conversation can make a difference
Leon recalls a client who initially established a U.S. banking relationship to manage overseas funds. A few years later, the client’s child came to the United States for school. The family then purchased a home in Southern California and arranged financing. As the client’s business expanded into the United States, the next need was a business account and cash-management services.
“From opening an account, to purchasing a home, to starting a company, these may look like different needs. But they are really the arrangements one family makes at different stages of life.”
When a bank already understands a client’s background, new banking needs can build on an existing relationship instead of starting from zero.
Start with the fuller picture
For families who are new to the United States, managing income across borders, or preparing for what comes next, the most useful first step is often sharing the fuller picture. Understanding where a family is headed can make it easier for the bank to identify banking services that may become relevant as needs arise.
To discuss cross-border banking needs that may fit your circumstances, contact New Omni Bank.
This article is adapted from content originally published in collaboration with Chinese L.A. Daily News.
The information provided in this blog is for general informational purposes only and should not be considered legal, financial, or investment advice. All content is subject to change without notice. Please consult with a qualified professional or contact New Omni Bank directly for personalized guidance or the latest product information.